
3:1 is the widely used minimum for a good LTV to CAC ratio; below 1:1 means acquiring a customer costs more than that customer returns, while above 5:1 can signal underinvestment in growth. But clearing the minimum doesn't mean you should increase your advertising budget.
A forecast isn't cash, and an attractive average isn't proof that every channel works. Before celebrating your ratio, check what counts as customer value, how quickly acquisition costs come back, and which customers generate the margin. Otherwise, you can scale a convincing spreadsheet straight into a cash shortage.
What LTV to CAC Means and Why 3:1 Is the Starting Point
A seemingly healthy ratio can still be a bad deal. If customer value depends on purchases that never happen, or arrives after you've exhausted your cash, the headline number won't protect the business.
Customer lifetime value, or LTV, measures the value a customer generates throughout the relationship. For growth decisions, use gross-profit-based value rather than first-order revenue. Customer acquisition cost, or CAC, is the sales and marketing investment required to win a new customer, including the people and systems involved.
Think of CAC as the price of buying a rental property and LTV as the rent it collects over its life. The comparison helps you judge whether the building earns its keep, but collecting rent isn't the same as keeping it after expenses.
How to Read the Ranges
Capterra's explanation of CAC versus lifetime value identifies approximately 3:1 as a healthy benchmark, below 1:1 as acquisition spending exceeding customer value, and substantially above 5:1 as a possible sign of underinvestment.
Use those boundaries as decision categories:
- Value destruction: Acquisition costs exceed the customer's contribution. More volume makes the underlying problem bigger.
- Thin economics: Customer value exceeds acquisition cost, but the remaining contribution may not adequately cover overhead, financing, and operating risk.
- Scalable potential: The relationship leaves enough contribution to investigate expansion, provided retention and cash timing hold.
- Possible missed opportunity: Strong economics justify testing additional investment rather than polishing an already impressive ratio.
The territory between acquisition break-even and the common growth benchmark deserves scrutiny. It's not automatically unprofitable, but it leaves less room for mistakes.
Practical rule: Treat the ratio as permission to investigate growth, not permission to approve the budget.
The ratio doesn't independently prove profitability. You still need to establish that the margin is real, customers stay as expected, and the business can afford the wait.
What a Good LTV to CAC Ratio Looks Like by Industry
Four of the six rows below describe one industry. That should tell you how thin reliable benchmarks are outside software.
Benchmark LTV:CAC ratios by business model
| Business model | Source and year | Median ratio | Top quartile | Notes |
|---|---|---|---|---|
| B2B SaaS | ConversionBench, 2024 | 3.8x | 6.5x | Median for B2B software |
| SaaS | Benchmarkit research summarized by RockingWeb, 2024 | Approximately 3.6x | Not reported | SaaS research summary |
| Public SaaS | KeyBanc's 2024 survey, reported by Jumpstart Partners | 4.2x | Not reported | Private SaaS averaged 3.1x, a different measure from the public-company median |
| SaaS, 342 companies | 2025 benchmark summary discussed with SaaS Capital's LTV guidance | 4.1x | 7.8x | Up from roughly 3.6–3.7x during 2022–2024 |
| E-commerce | No reliable median established here | Not established | Not established | Repeat purchases and margin drive value |
| Local and franchise services | No reliable median established here | Not established | Not established | Referrals, reviews, and offline conversions affect value |
Read the spread as carefully as the middle. The reported SaaS medians cluster in a narrow band, while the top quartile sits far above them, which means the best operators hit no ceiling at the median. Treat the common benchmark as the floor it is: a business clearing it has earned the right to test more spend, and a business sitting near top-quartile territory should ask whether retention, pricing power, or acquisition efficiency is doing the work, because that answer decides whether the advantage survives a bigger budget.
Cash decides the rest. A ratio comfortably above the floor still fails if contribution arrives after the payroll it needs to fund, so measure any benchmark against your payback timeline before you celebrate it.
Build Your Own Baseline Where No Median Exists
Recurring subscriptions make customer behavior easier to model than occasional purchases or emergency service calls. An e-commerce brand has to account for reorder patterns, returns, and promotional dependence before a single ratio means anything. A local operator has to separate a one-time job from an ongoing service relationship, and a franchise location with open appointment slots monetizes demand differently from one whose technicians are already booked out.
So compare like with like. Match the model, subscriptions against subscriptions and maintenance customers against maintenance customers. Match the maturity, since an early forecast deserves no comparison with a seasoned business's observed retention. Match the accounting, because revenue-based LTV and margin-adjusted LTV aren't interchangeable.
The empty rows are the honest answer for most businesses. Your channel and cohort trends are more actionable than an industry leaderboard, so build the baseline from your own retention curve and let the SaaS numbers set direction. The grading happens against your own cohorts.
How to Calculate Your LTV to CAC Ratio Step by Step
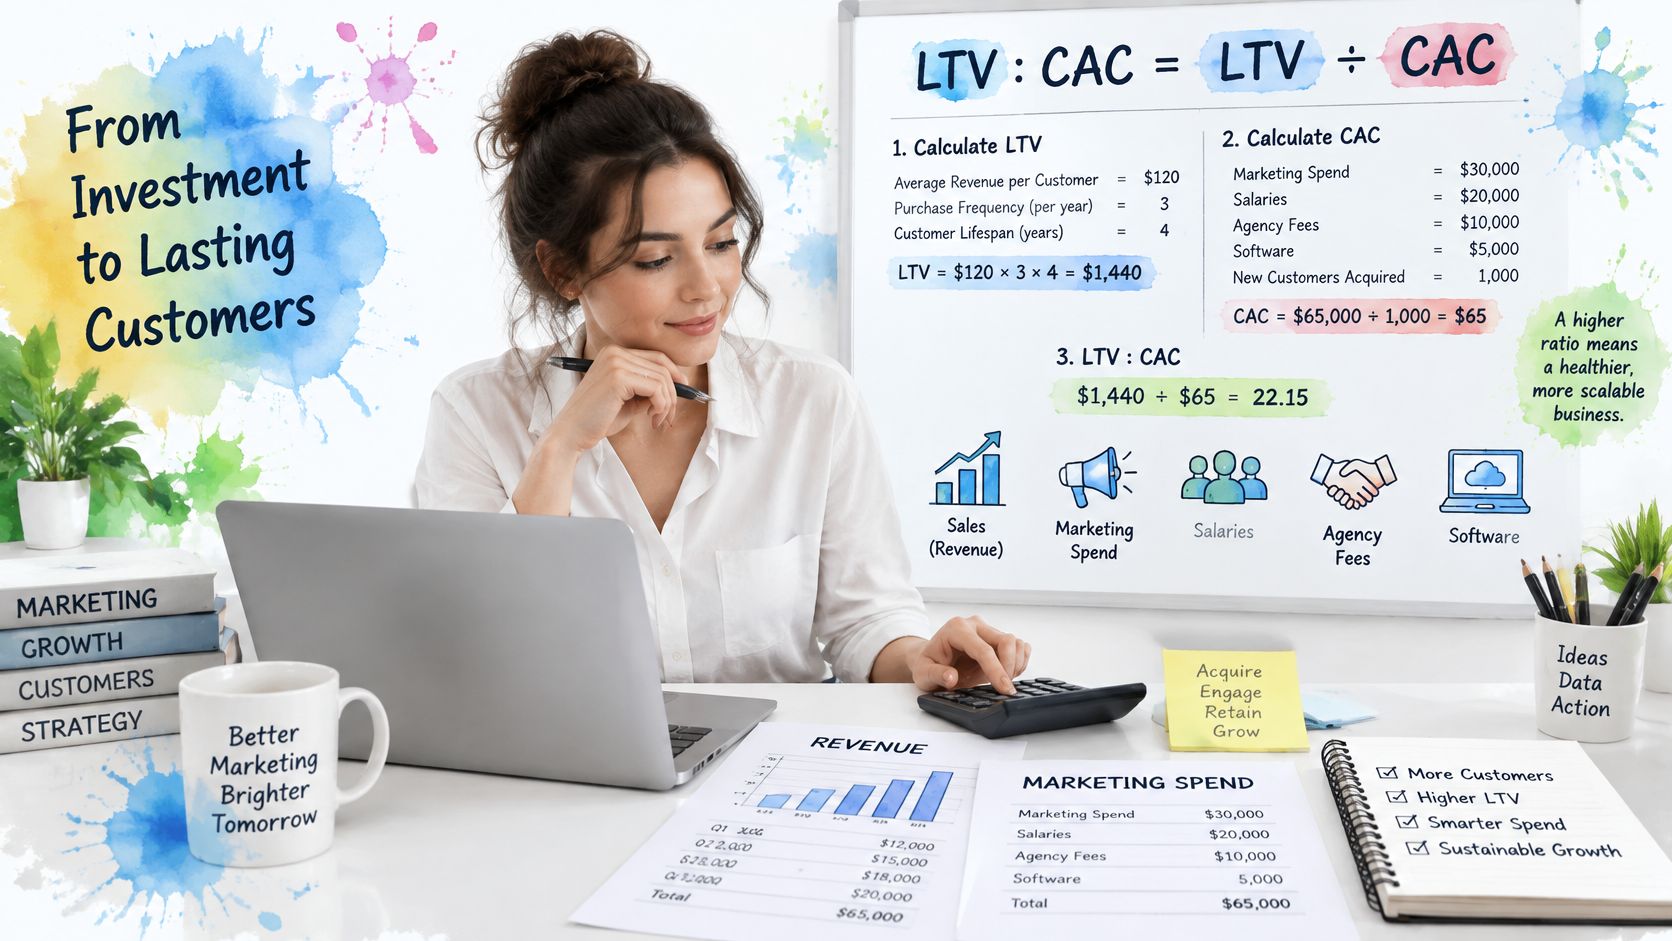
LTV:CAC = LTV ÷ CAC. The Corporate Finance Institute's customer lifetime value guide illustrates the calculation with $900 in lifetime value divided by $300 in acquisition cost, producing 3.0x.
The arithmetic is easy. Defining comparable inputs is the work.
Build the Calculation From Your Ledger
Calculate fully loaded CAC. Pull twelve months of sales and marketing expenses, including acquisition-related salaries, agency fees, creative, and software, then divide by new customers acquired. In a hypothetical business, $60,000 ÷ 200 new customers = $300 CAC; align spending with the customers it produced when your sales cycle creates a delay.
Build margin-adjusted LTV. For a straightforward repeat-purchase model, multiply average order value by purchases per year, gross margin percentage, and average customer lifespan in years. Using illustrative inputs, $150 × 3 annual purchases × 40% gross margin × 5 years = $900 LTV.
Divide comparable values. In that scenario, $900 ÷ $300 = 3.0x. Don't combine one channel's acquisition cost with the lifetime value of your entire customer base unless you've confirmed that customer quality is comparable.
Stress-test the assumptions. Shorten the assumed lifespan, remove unproven repeat orders, and recalculate using less favorable margins. As a conservative working practice, average retention over at least six months rather than extrapolating from an unusually strong month.
Save the cohort, not just the result. Record acquisition month, channel, customer count, costs, realized margin, and forecast margin separately. That lets you see whether later purchases validate the original estimate.
Use a consistent customer acquisition cost calculation before comparing campaigns. If one report includes sales salaries and another includes only media spend, you're comparing accounting choices rather than marketing performance.
Keep Forecasts Separate From Collected Value
When history is limited, build provisional LTV from observed purchase behavior. With fewer than six months of cohort history, start with first- and second-order gross profit, label any extension as a forecast, and update it as transactions arrive.
Avoid counting the same cost twice. Acquisition expenses belong in CAC; fulfillment and service-delivery costs reduce customer margin. If you extend the calculation to contribution margin, document how ongoing retention expenses are deducted.
A spreadsheet should distinguish what customers have already contributed from what you still hope they'll contribute.
The illustrative result clears the conventional floor. It doesn't yet establish that the business can finance acquisition at a higher volume. That requires a cash-recovery test.
Why CAC Payback Changes What a 3:1 Ratio Means
You usually commit acquisition spending before collecting the customer's lifetime contribution. That gap determines how much growth your cash balance can support, even when the projected economics look attractive.
CAC payback measures how long customer gross profit takes to cover acquisition cost. MetricHQ's CAC payback guidance reports SaaS benchmark summaries with a roughly 15–18-month median, while top-quartile companies recover CAC in fewer than 12 months.
Translate the Ratio Into a Cash Decision
The following combinations are decision scenarios, not universal industry thresholds.
Ratio and payback combinations and what they signal
| Ratio | CAC payback | What it signals | What to do |
|---|---|---|---|
| 3:1 | Under 6 months | Returned cash can help fund further growth | Scale this cohort within operating capacity |
| 3:1 | 18 months or more | Viable on paper, but cash-hungry | Cap spending to what your runway covers |
| Below 1:1 | Never recovers under the stated lifetime economics | Each new customer destroys contribution | Fix the offer or acquisition economics before scaling |
| Above 5:1 | Any | Possible underinvestment, not automatic proof | Test a higher budget with holdouts |
| Any | Supported only by forecast LTV | Customer economics remain unconfirmed | Treat the result as provisional until cohorts validate it |
Calculate payback from cumulative cohort gross profit when purchases are irregular. A monthly-average formula can conceal a long wait for a seasonal reorder or annual renewal.
Use contribution margin analysis to check whether discounts, fulfillment, refunds, and variable service costs leave enough cash after the sale. Revenue recovery isn't acquisition-cost recovery if most of the revenue pays for delivery.
Set a payback ceiling against available cash, not the most flattering benchmark. In a hypothetical business that can fund twelve months of acquisition losses, a twelve-month payback leaves little safety margin once payroll, inventory, and unexpected expenses enter the picture.
Your cash runway is a constraint, not a target to use up. Reserve a buffer, model slower collections, and assess each channel separately. A fast-paying channel shouldn't finance unlimited expansion of a slow-paying one.
Segment the Ratio by Channel and Customer Type
Shopify's reporting on customer acquisition models found that 68% of retail marketers experienced rising CAC, while one in five retail brands spent $251–$500 to acquire each customer. When acquisition gets more expensive, a portfolio-average ratio hides exactly where the money goes.
A blended 3:1 can sit on top of channel economics that deserve very different decisions. Say paid search produces 4:1 and paid social produces 1.5:1; with the right acquisition-spend weighting, the combined result looks like the 3:1 floor. That is a hypothetical illustration of how averages conceal weak cohorts, not proof that the lower-ratio channel loses money before overhead.
Calculate the blend the right way: total customer lifetime contribution divided by total acquisition cost.
A simple average of channel ratios ignores how much you spent in each.
Compare Cohorts on the Same Basis
Privacy restrictions and fragmented attribution limit what platform reports can establish. Reconcile campaign records with customer and transaction data through cross-channel attribution, then compare segments on equal footing:
- Paid search against paid social. Separate existing demand from incremental customers.
- Referrals and organic traffic. Allocate the labor and program costs behind acquisition instead of treating these customers as free.
- Individual locations. Include local margins, sales follow-up, and service capacity.
- Customer reactivation. Keep repeat-customer economics separate from new-customer CAC.
A lower-ratio segment can still earn budget when it pays back quickly, fills otherwise unused capacity, or supports a deliberate expansion. Give that exception an explicit budget and a review date. The opposite failure is quieter: an excellent ratio may belong to a small channel that has never faced a meaningful expansion test. Raise spend experimentally and watch the contribution the additional customers generate.
Cohort test: Judge customers after margin, refunds, fulfillment, discounts, and retention costs, not after the advertising dashboard declares victory.
Where practical, run holdouts to check whether the campaign caused the purchases. Attribution assigns credit; incrementality tests whether the purchases would have happened anyway.
Worked Examples for Four Business Models
Illustrative LTV to CAC cases and what each number hides
A 3:1 result can justify expansion at one company and conceal a cash problem at another. These four cases use hypothetical inputs to show how the verdict changes once you look past the ratio.
| Business | CAC | Ratio | What the number hides |
|---|---|---|---|
| E-commerce skincare brand | $45 | 4.0x, from $180 gross-margin LTV | First two orders recover CAC in about 60 days |
| Local HVAC company | $350 | Approximately 6.9x, from $2,400 gross-margin LTV | A single repair provides insufficient value; maintenance drives the economics |
| B2B SaaS at $5,000 annual contract value | $6,000 | Approximately 3.1x | $18,750 five-year LTV assumes 75% gross margin; payback is about 19 months |
| Subscription box on forecast LTV | $90 | 3.0x, from $270 forecast LTV | The forecast spans 24 months, but cohorts show about nine months of purchases and roughly 1.0x realized value |
The skincare row is the easy case. Recovery arrives quickly, and projected value has room to spare. The open question is behavioral: do customers still reorder at full price once introductory discounts end? Check reorder rates among full-price cohorts before scaling spend.
The SaaS row looks comfortable at 3.1x and isn't. Recovering $6,000 takes roughly 19 months of gross profit, so the company funds nearly two years of acquisition cost before the account turns contribution-positive. Annual prepayment eases the cash strain without shortening the underlying payback math, and a floor of 3:1 leaves little room for churn inside that window. Finance this growth only if the balance sheet tolerates the wait.
The HVAC math rewards a closer read.
Put the $350 acquisition cost against $2,400 in gross-margin lifetime value and you get roughly 6.9x ($2,400 ÷ $350). The first repair job contributes less than CAC, so the entire result rests on the maintenance plan. Before crediting that ratio, verify three inputs: actual plan enrollment rather than theoretical eligibility, delivery margin after the labor and parts those visits consume, and renewal persistence before assigning long-term value. If adoption disappoints, the true ratio falls toward whatever a single repair supports.
The subscription box deserves the harshest challenge. A 3.0x forecast built on 24 months of retention means little when realized cohorts stop buying around month nine and deliver roughly 1.0x. Spending against that forecast finances growth on value that hasn't been earned. Until newer cohorts prove longer persistence, run the business on the realized figure.
The formula never changes across these rows. The verdict does. A maintenance agreement, a renewal assumption, a reorder forecast: none of it counts as value until customers follow through.
How to Raise LTV and Lower CAC Without Cutting Growth
Improve the economics by earning more contribution from each customer, paying less to acquire suitable customers, or doing both. Start with operational leaks before assuming you need a bigger audience.
Raise Customer Value Through Better Follow-Through
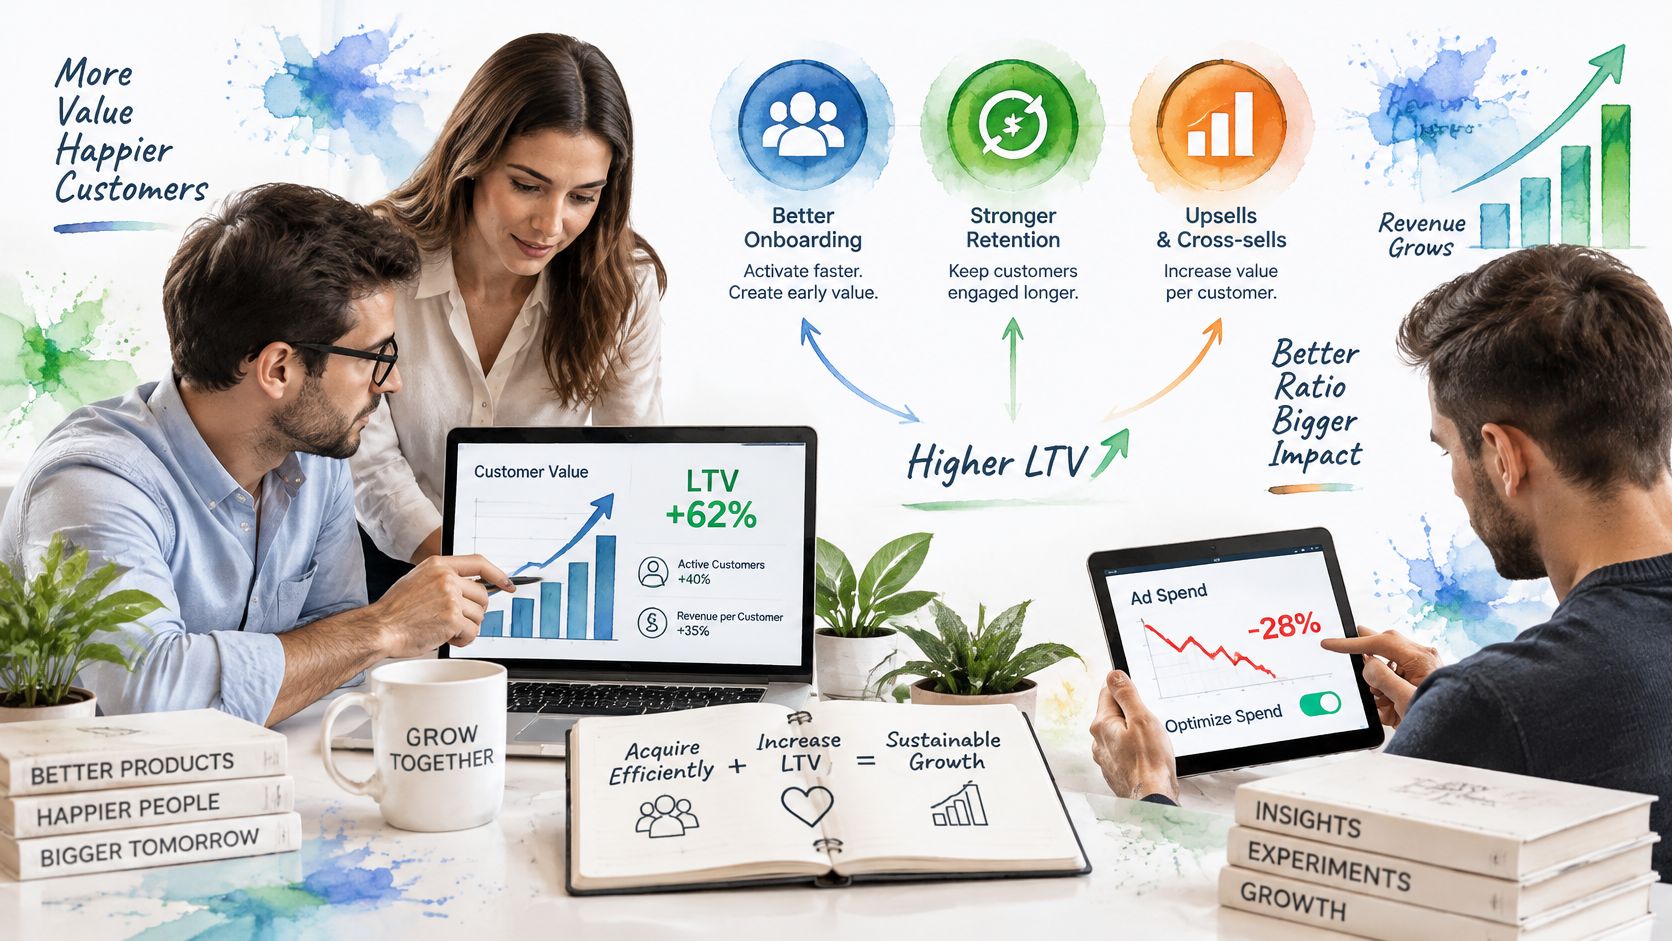
- Retention: Use post-purchase follow-up, reorder reminders, and a service calendar. Assign an owner to overdue follow-ups so the process doesn't depend on someone remembering.
- Expansion: Offer relevant bundles, maintenance plans, or cross-sells after the initial purchase proves useful. Measure added contribution, not merely a larger invoice.
- Referrals: Request honest reviews after successful delivery and give satisfied customers a clear referral path. Attribute referred customer value separately rather than adding it to the original buyer's LTV and counting it again elsewhere.
A practical customer lifetime value improvement plan connects each action to an observable behavior: another purchase, a renewal, or a qualified referral.
At The Advertising Suite, our Growth-Tech Hybrid approach combines human-led strategy with a built-in CRM and review management ecosystem. These are core parts of connecting customer experience to revenue, not optional extras attached to media buying.
Reduce Acquisition Waste Before Reducing Ambition
Conversion comes first. Fix slow landing pages, unnecessary form fields, unclear offers, and poor lead follow-up before purchasing more traffic. Test qualified sales outcomes, since a shorter form can produce more inquiries without producing better customers.
Targeting requires exclusions. Review search terms, placements, locations, and lead quality. Remove demonstrably unsuitable demand, but don't cut a campaign because the sales cycle hasn't finished.
Channel mix requires reallocation. Move investment toward cohorts whose contribution and cash recovery support expansion. Keep a controlled testing budget so today's strongest channel doesn't become tomorrow's only option.
Optimize for total profitable contribution, not the prettiest ratio.
Cutting acquisition investment can improve the displayed ratio while shrinking total profit. Judge changes by additional contribution after additional acquisition cost, with service capacity and cash requirements included.
A smaller business with a beautiful dashboard isn't necessarily a better business. The objective is sustainable growth you can fund and deliver.
Confirm Your Ratio Before You Scale Ad Spend
Treat 3:1 as the floor for a decision, not the decision. Approve expansion cohort by cohort: margin-adjusted LTV above the threshold, retention or reorder behavior already observed, and CAC payback inside the cash window you can fund.
Hold back any group still proving itself. If value is thin or cash returns too slowly, change the economics before buying more reach; a bigger audience often converts worse than the first one.
Use incrementality testing when the budget step is large enough to change who sees the ads. The question is simple: does added spend create added contribution, or does it only claim credit for demand that would have closed anyway?
Keep Conversion Gains Accountable
At The Advertising Suite, AI drives a 372% increase in lead-to-revenue conversion. That lift earns more budget only after it survives the same checks: customer margin, acquisition cost, and cash recovery by cohort.
Assign one owner to review those cohorts monthly. Have them record what changed, whether realized contribution matched the forecast, and whether the next increase still fits the cash window.
The Advertising Suite combines growth strategy, advertising execution, and an integrated CRM and review management ecosystem to connect acquisition spending with customer value. Visit The Advertising Suite to Book a Growth Consult and review your CAC, cohort margins, and payback, or Explore the Membership for access to the proprietary CRM and automated review management software.